


Subscribe
The Canadian Pension Plan (CPP) managed $731.7 billion in 2025, making it one of the biggest pension funds in the world. Quebec also independently manages its own fund, the Quebec Pension Plan (QPP), raising Canada’s total managed assets to one trillion dollars. These funds were built on a legally mandated payment scheme that ensures every Canadian receives financial support upon retirement.
But citizen contributions alone can’t raise so much capital. Instead, the CPP and QPP carefully invest these contributions to grow the funds’ overall value. This allows them to keep up with the needs of Canada’s aging population without disproportionately burdening younger working citizens. By 2075, between 22.6 and 32.5 per cent of Canada’s population will be over 65 years old.
Countries around the world face a similar challenge. Longer lifespans and lower birth rates mean there’s more demand on pension funds with fewer people contributing to them. And yet, many wealthy European countries – such as France, Germany, and Luxembourg – continue to rely primarily on pay-as-you-go systems that don’t grow through investments.
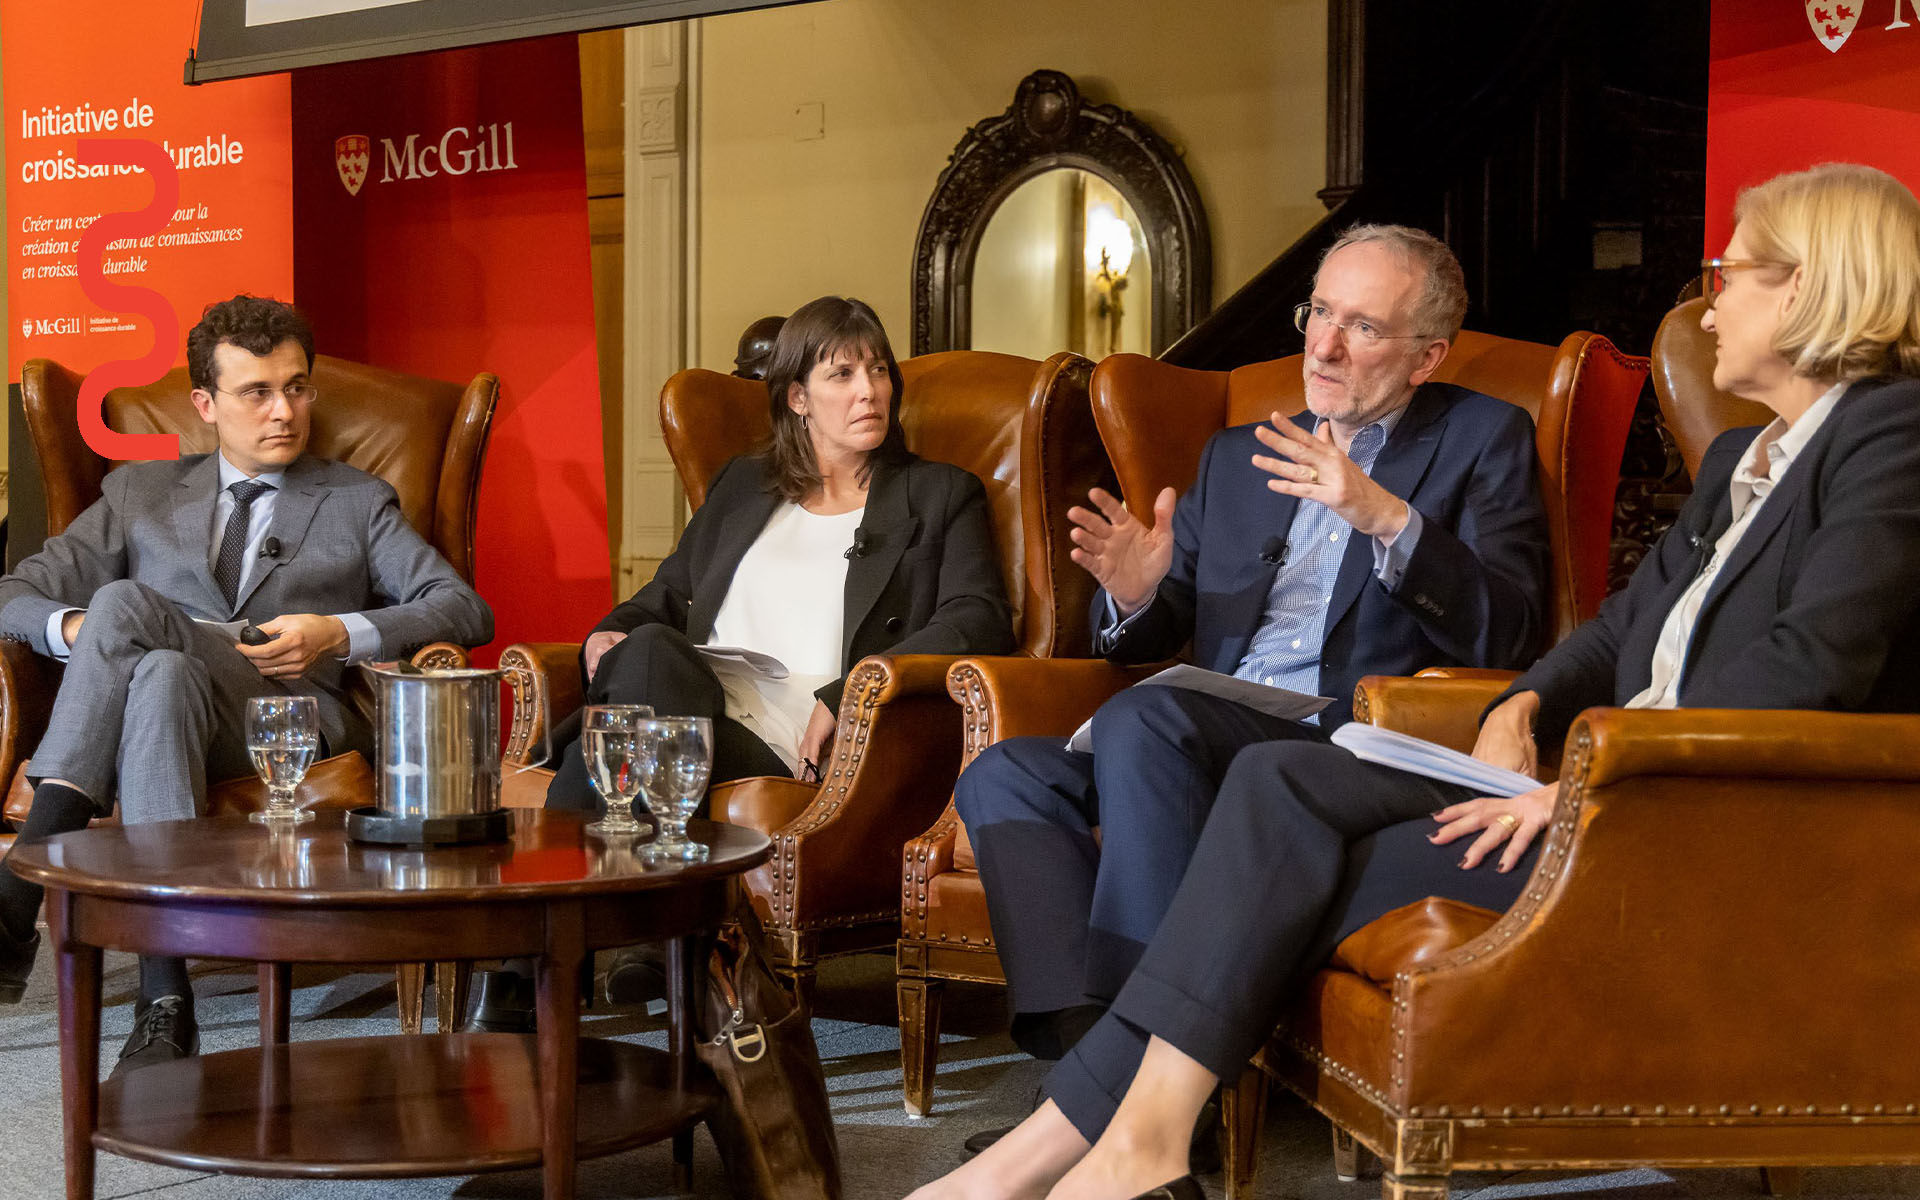
For Patrick Augustin and Sebastien Betermier, both associate professors of finance at McGill University, countries with pay-as-you-go systems are missing important economic growth opportunities. Invested pension assets can support retirement incomes, provide long-term capital to the economy, and foster broader household participation in capital markets.
That was Mario Draghi’s theory, the former governor of the European Central Bank, which he documented in a 2024 report. He said one of the reasons Europe was lagging behind the United States and China was a lack of capital from pensions to deploy in the economy.
Augustin and Betermier examined this issue in a recent paper. The findings suggest that Draghi may have had a point.
Saving productively
From 2002 to 2023, the gap between Europe’s gross domestic product (GDP) and the United States nearly doubled. Draghi’s 2024 report attributes this in part to an insufficient supply of risk capital – money invested in risky assets such as public and private firms or infrastructure projects.
This is where pension funds can help, said Betermier. Pension fund investments tend to be long-term and patient, making them a source of capital growth. This can create a virtuous cycle that benefits retirees, current working-age citizens, and the economy as a whole.
“You have a win-win-win situation, possibly,” said Augustin.
The first win: a bigger fund to support an aging population. Second, increased investment in important economic sectors, which could lead to more employment and higher salaries. And third, a surprising finding from their study: as pension funds become more productive, individual households tend to place their voluntary savings into risk capital investments as well. This means more money circulating the economy, and more personal financial growth to support people in retirement.
This is in contrast to pay-as-you-go systems, where government collects money from citizens via taxes or mandated pension contributions, which is then redistributed to current retirees. Here, the fund doesn’t grow on its own, nor does it provide risk capital for private or public ventures. It simply moves money from current workers to retirees, with the expectation that workers will benefit from the same system once they too reach retirement age.
Augustin and Betermier found that countries with capitalized pension systems, over the past 30 years, hold two to three times more risk capital per worker than pay-as-you-go systems.
“That’s a massive difference,” said Betermier. “It’s incremental. But through the years, you see the savings and the compound returns.”
A matter of time
For countries that have not yet capitalized their pension funds, time is of the essence, said Betermier.
“Countries that have gone through these reforms 20 years ago are in a much better fiscal situation today as a result,” he said. “And creating that virtuous cycle becomes harder and harder the longer you wait.”
This is because pay-as-you-go systems are increasingly costly to maintain. Active workers have to contribute higher percentages of their income to sustain the current system. In uncapitalized countries like France and Germany, upwards of 25 percent to 30 percent of a worker’s income may now be needed to pay for retirees, he said.
This increasing financial commitment to retirees is not just a strain on the current system, but it also makes it harder to transition to a capitalized pension system, said Betermier. Countries looking to transition need to build up capital with which to invest. To do that, workers must pay 1) for current retirees’ pensions and 2) an additional sum to help establish the investment fund. But when 30 percent of a worker’s income already goes towards sustaining the current system, there is little left over to build a new pool of capital. And as a country waits to adopt a capitalized pension fund, younger workers will need to contribute a higher proportion of their income to support the growing number of retirees.
The silver lining in all of this is that there’s no one way to reform a national pension strategy, said Betermier. Augustin and Betermier’s study highlighted three different countries using three different strategies to prioritize risk capital accumulation. Canada and Quebec have their own centralized funds, which citizens are required to contribute to. Australia requires employers to invest a portion of employee income into a superannuation fund (the employee can choose which fund they prefer). Sweden uses a hybrid approach: workers can choose to invest in the capitalized national pension fund, or pick up to five funds from more than 650 domestic and international mutual funds.
“It’s good news, actually,” said Betermier, “there are multiple pathways ahead.”
The path forward may be culturally or context-specific for each country. But the lesson is the same everywhere: the sooner a country acts on pension reform, the more room they have to build a system prepared to support generations to come.
Featured experts
Associate Professor, Finance; Director, McGill Luxembourg Centre for Finance.

Associate Professor, Finance
Writers
Eric Dicaire, Managing Editor, Delve
The cover image for this article was generated using AI.